 Explore Franchising Opportunities

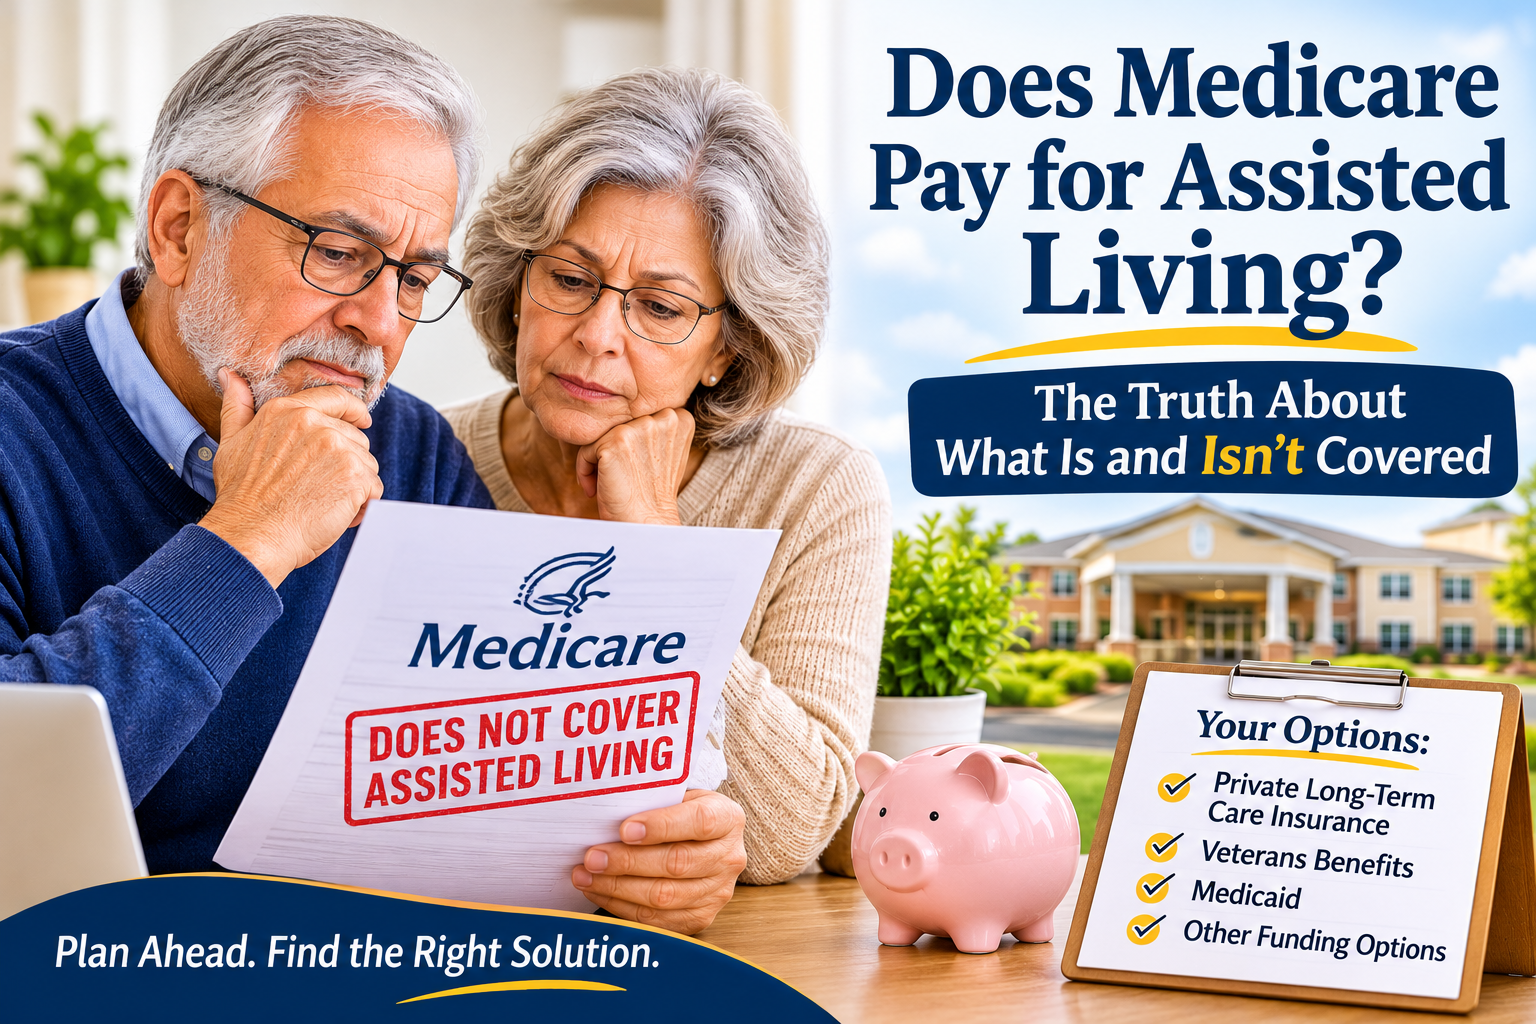
One of the most persistent assumptions families make when an aging parent needs care is that Medicare will cover the bills. After all, Medicare has supported their hospital visits, physician checkups, and prescription drugs throughout retirement.
However, that does not mean Medicare is useless once a parent moves into a community. Understanding the strict distinction between custodial care and skilled medical care—and knowing the actual programs that fund long-term care—can save your family thousands of dollars and prevent costly financial missteps.
Why Doesn’t Medicare Pay for Assisted Living?
To understand why Medicare denies assisted living claims, you have to look at how the program defines care:
- Skilled Medical Care: Medically necessary treatments ordered by a physician and delivered by licensed healthcare professionals (e.g., wound debridement, physical therapy, IV therapy, post-stroke rehabilitation).
- Custodial Care: Non-medical assistance with Activities of Daily Living (ADLs)—including bathing, dressing, eating, using the restroom, transferring from a bed to a chair, and routine medication reminders.
Under federal statute, Medicare is strictly a health insurance program, not a long-term care program.
As clearly outlined in official coverage guidelines from Medicare.gov on long-term care, Medicare does not cover custodial care when that is the only type of care needed. Because assisted living communities are built primarily around room, board, and custodial support, their monthly base rates fall outside Medicare’s mandate.
What Medicare Will Pay for While Living in Assisted Living
While Medicare won’t pay your parent’s monthly community invoice, their Medicare coverage continues to operate just as it did when they lived at home.
If your parent resides in an assisted living community, Medicare Parts A, B, and D still cover approved medical interventions:
- Physician Services (Part B): Outpatient doctor visits, whether your parent travels to a clinic or uses visiting physicians who hold office hours directly inside the assisted living facility.
- Physical, Occupational, and Speech Therapy (Part B): If your parent suffers a decline in balance or an injury, a physician can order on-site physical or occupational therapy inside the community, billed directly through Part B.
- Prescription Medications (Part D): Standard covered prescriptions continue to be subsidized, whether delivered to the community by an institutional pharmacy or picked up locally.
- Durable Medical Equipment (Part B): Medically necessary walkers, wheelchairs, oxygen equipment, or hospital beds prescribed by a doctor are covered subject to standard coinsurance.
- Hospice and Palliative Care (Part A): If a resident faces a terminal illness, Medicare covers pain management, nursing visits, medical equipment, and emotional counseling delivered directly within their assisted living apartment.
What About Medicare Advantage (Part C)?
Many families ask whether private Medicare Advantage (Part C) plans cover assisted living.
While some Medicare Advantage plans offer supplemental benefits—such as adult day care allowances, limited meal delivery after hospital discharges, or non-emergency medical transportation—they still do not pay for assisted living room and board or round-the-clock custodial staffing. Any supplemental personal care hours offered by Part C plans are short-term, capped, and designed to augment care rather than pay monthly facility fees.
How Families Actually Pay for Assisted Living
Because Medicare does not pay the primary bill, families combine alternative financial mechanisms to cover monthly costs. Here are the most effective funding avenues:
1. Private Long-Term Care Insurance (LTCI)
Unlike standard medical insurance, private long-term care policies are specifically designed to pay for custodial care. If your parent purchased a policy prior to developing chronic conditions, it will typically pay out a daily or monthly cash benefit for assisted living once they require assistance with two or more ADLs.
2. Veterans Aid and Attendance Benefits
War-era veterans and their surviving spouses may qualify for the VA Aid and Attendance pension. This tax-free monthly benefit is added to standard VA pensions for veterans who require assistance with daily tasks, providing financial assistance toward assisted living or memory care expenses.
3. Medicaid Home and Community-Based Services (HCBS) Waivers
While Medicare does not cover assisted living, Medicaid often helps pay for eligible services for individuals who meet strict state-level income and asset limits. Most states operate 1915(c) HCBS Waivers, which help pay for the personal care and staffing services delivered inside participating assisted living facilities, though the family or resident generally remains responsible for room and board.
4. Bridge Loans and Life Insurance Settlements
- Senior Living Bridge Loans: Short-term, line-of-credit financing that covers move-in and monthly fees while the family waits for a home to sell or VA benefits to be approved.
- Life Settlement / Policy Conversions: Certain whole or universal life insurance policies can be converted into an immediate Long-Term Care Benefit Account, paying tax-free monthly installments directly to the assisted living community. Eligibility and tax treatment depend on the policy and arrangement.
Medicare vs. Medicaid: Understanding the Difference
| Feature | Medicare | Medicaid |
|---|---|---|
| Program Type | Federal health insurance | Joint Federal and State assistance |
| Eligibility | Age 65+ or specific disabilities (non-means-tested) | Low-income and asset-limited seniors |
| Assisted Living Room & Board | Not Covered | Generally not covered |
| Assisted Living Personal Care | Not Covered | May be covered in participating states through HCBS programs |
| Doctor Visits & Medical Care | Covered under applicable Parts A and B benefits | Covered services vary by state |
| Skilled Nursing Facility (Post-Hospital) | Limited short-term coverage when eligibility requirements are met | May cover eligible long-term nursing facility care |
How Trua Protects You from Financial Blind Spots (100% Free)
Budgeting for assisted living can feel overwhelming. Many communities charge deceptive “a la carte” pricing structures, where the base rent looks affordable, but every daily reminder, shower assistance, or medication delivery adds unexpected surcharges to the monthly bill.
At Trua: The Senior Living Locators, we believe families deserve total clarity:
- Geriatric Clinical Leadership: Founded by Dr. Matt Staley, a Doctor of Physical Therapy and Geriatric Certified Specialist with more than 20 years of clinical experience in senior living settings.
- Comprehensive Care & Financial Assessments: We start with an objective senior living care evaluation to determine your parent’s exact physical care tier, preventing surprise level-of-care price hikes after move-in.
- Transparent Community Matching: We only recommend communities that match your parent’s true clinical needs and long-term financial budget.
- Resource Connections: We connect families with trusted elder law attorneys, veterans benefits specialists, and senior financial planners to unlock hidden benefits.
- 100% Free of Charge: All of Trua’s advisory services, community tours, and placement advocacy are completely free to families.
Find the Right Care Community Within Your Budget
Navigating senior living financing doesn’t have to be a solo journey. Our experienced local advisors can help you map out care requirements, explore funding options, and find high-quality communities that fit your family’s budget.
Start with a free assessment or speak directly with an advisor to explore your options.